Today’s housing market splits into four distinct types. You’ve got cash buyers, buyers financing a purchase, owners who feel locked into a low rate, and builders with homes to sell.
Dated: June 27 2024
Views: 63
Should you buy a home now or should you wait? That’s a big question on many people’s minds today. And while what timing is right for you will depend on a lot of other personal factors, here’s something you may not have considered.
If you’re able to buy at today’s rates and prices, it may be better to focus on time in the market, rather than timing the market.
Trying to time the market isn’t a good strategy because things can change. Here’s an example. For the better part of this year, projections have said mortgage rates will come down. And while experts agree that’s still what’s ahead, shifts in various market and economic factors have pushed back the timing of when that’ll happen. Here’s how that’s impacted homebuyers who’ve been sitting on the sidelines. As U.S. News says:
“Those who put off buying a home during the past few years as they were holding out for lower mortgage rates have been left out of the market . . . mortgage rates have stayed higher for longer than previously expected, keeping monthly housing payments elevated. In other words, affordability didn't improve for those who chose to wait.”
This is why timing the market may not pay off if you’re ready and able to buy now.
Delaying your plans also means missing out on the equity you’d gain if you went ahead with your purchase today. And the potential equity gains that are at stake may surprise you.
Each quarter, Fannie Mae releases the Home Price Expectations Survey. It asks over one hundred economists, real estate experts, and investment and market strategists what they forecast for home prices over the next five years. In the latest release, experts are projecting home prices will continue to rise through at least 2028 (see the graph below): 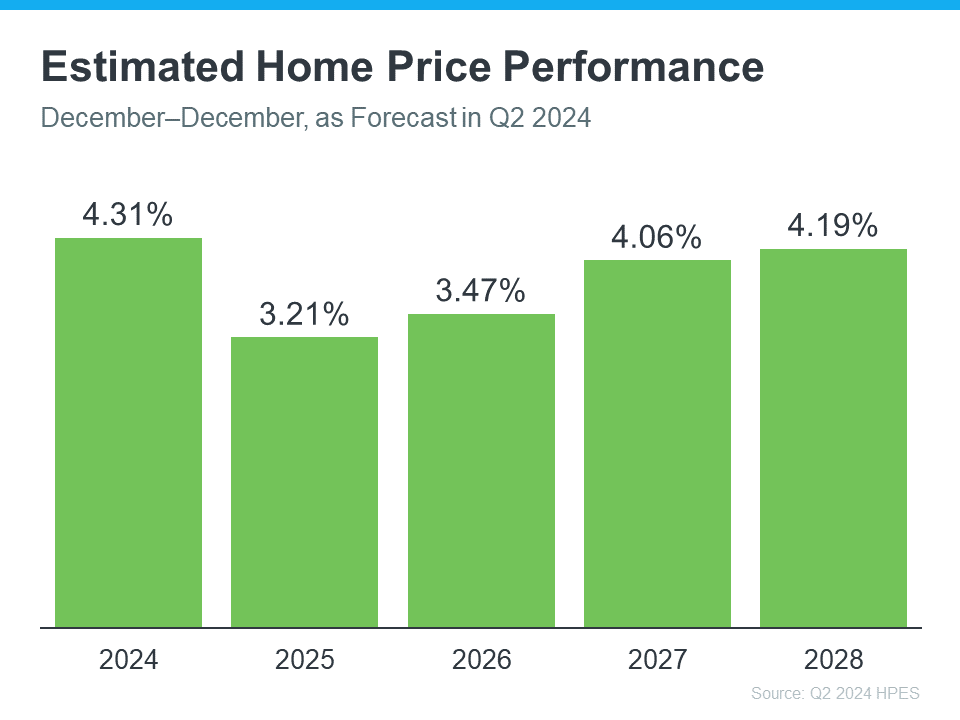
To give these numbers context, let’s take a look at a breakdown of what you stand to gain once you buy. The graph below uses a typical home’s value to show how a home could appreciate over the next few years using those HPES projections: 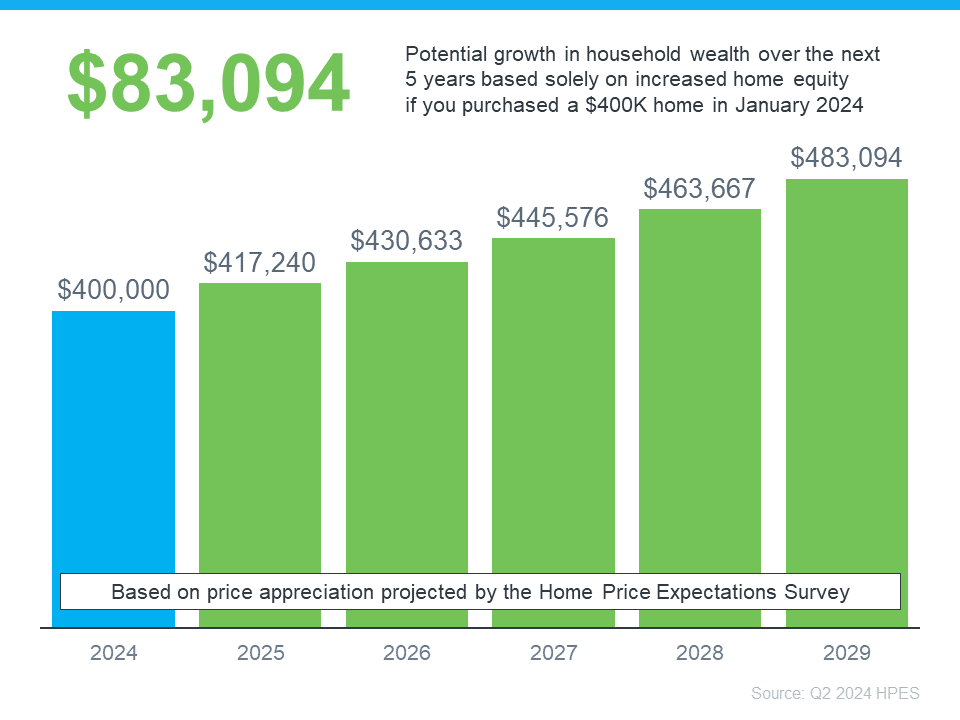
In this example, let’s say you went ahead and bought a $400,000 home at the beginning of this year. Based on the expert forecasts from the HPES, you could gain more than $83,000 in household wealth over the next five years. That’s not a small number.
This data helps paint the picture of why time in the market really matters.
Right now, you may be focused on what’s happening with mortgage rates and how those impact your monthly payment, but don’t forget to factor in home prices.
Prices are expected to continue climbing, just at a more moderate pace. And while a moderate rise in prices may not be fun for you now, once you own a home, that growth will be a huge perk. That’s the time in the market piece.
Sure, you could try timing the market, but the equity you’ll be missing out on in the meantime is something to seriously consider. If you’re ready and able to buy now, you have to decide: is it really worth waiting?
My Commitment to YOU!Navigating the world of real estate can feel overwhelming, but you don’t have to face it alone! I’m here to transform the experience of buying or selling your home int....
Today’s housing market splits into four distinct types. You’ve got cash buyers, buyers financing a purchase, owners who feel locked into a low rate, and builders with homes to sell.
If you're trying to buy a home, affordability is probably what keeps you up at night. And as you watch mortgage rates tick up again lately, it’s fair to wonder if you should just hit pause and
Selling your house this fall is absolutely doable. But there’s something you need to know about this time of year. Buyer activity typically starts to slow while the number of homes for
Summer's winding down, and if you've been thinking about selling, you might be wondering if you missed your chance. Better to wait until next year or even next spring, right?Not so fast. About one
 Wasatch Front Regional MLS - Salt Lake Board of REALTORS® All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties
consumers may be interested in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than EQUITY REAL ESTATE® - Prosper Group may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 23, 2026 2:03 PM UTC
Show More...
 Washington County Board of REALTORS® All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be
interested in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than EQUITY REAL ESTATE® - Prosper Group may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 23, 2026 2:17 PM UTC
Show More...
