Today’s housing market splits into four distinct types. You’ve got cash buyers, buyers financing a purchase, owners who feel locked into a low rate, and builders with homes to sell.
Dated: August 12 2026
Views: 12
If you're waiting for mortgage rates to fall a lot before you buy, you may be waiting a while. But before you get discouraged, there's a number working behind the scenes that's actually good for you right now. It's called the spread, and once you understand it, you may see today’s rates in a whole new light.
For starters, mortgage rates don't move on their own. They tend to follow the 10-year treasury yield, a number tied to how investors feel about the economy.
It’s not an exact science, since plenty of other factors can move it day to day, but broadly speaking, when the economy looks strong, that yield tends to climb over time. When the outlook gets shaky, it tends to ease. For over 50 years, the 10-year treasury yield and mortgage rates have moved almost in lockstep (see graph below):
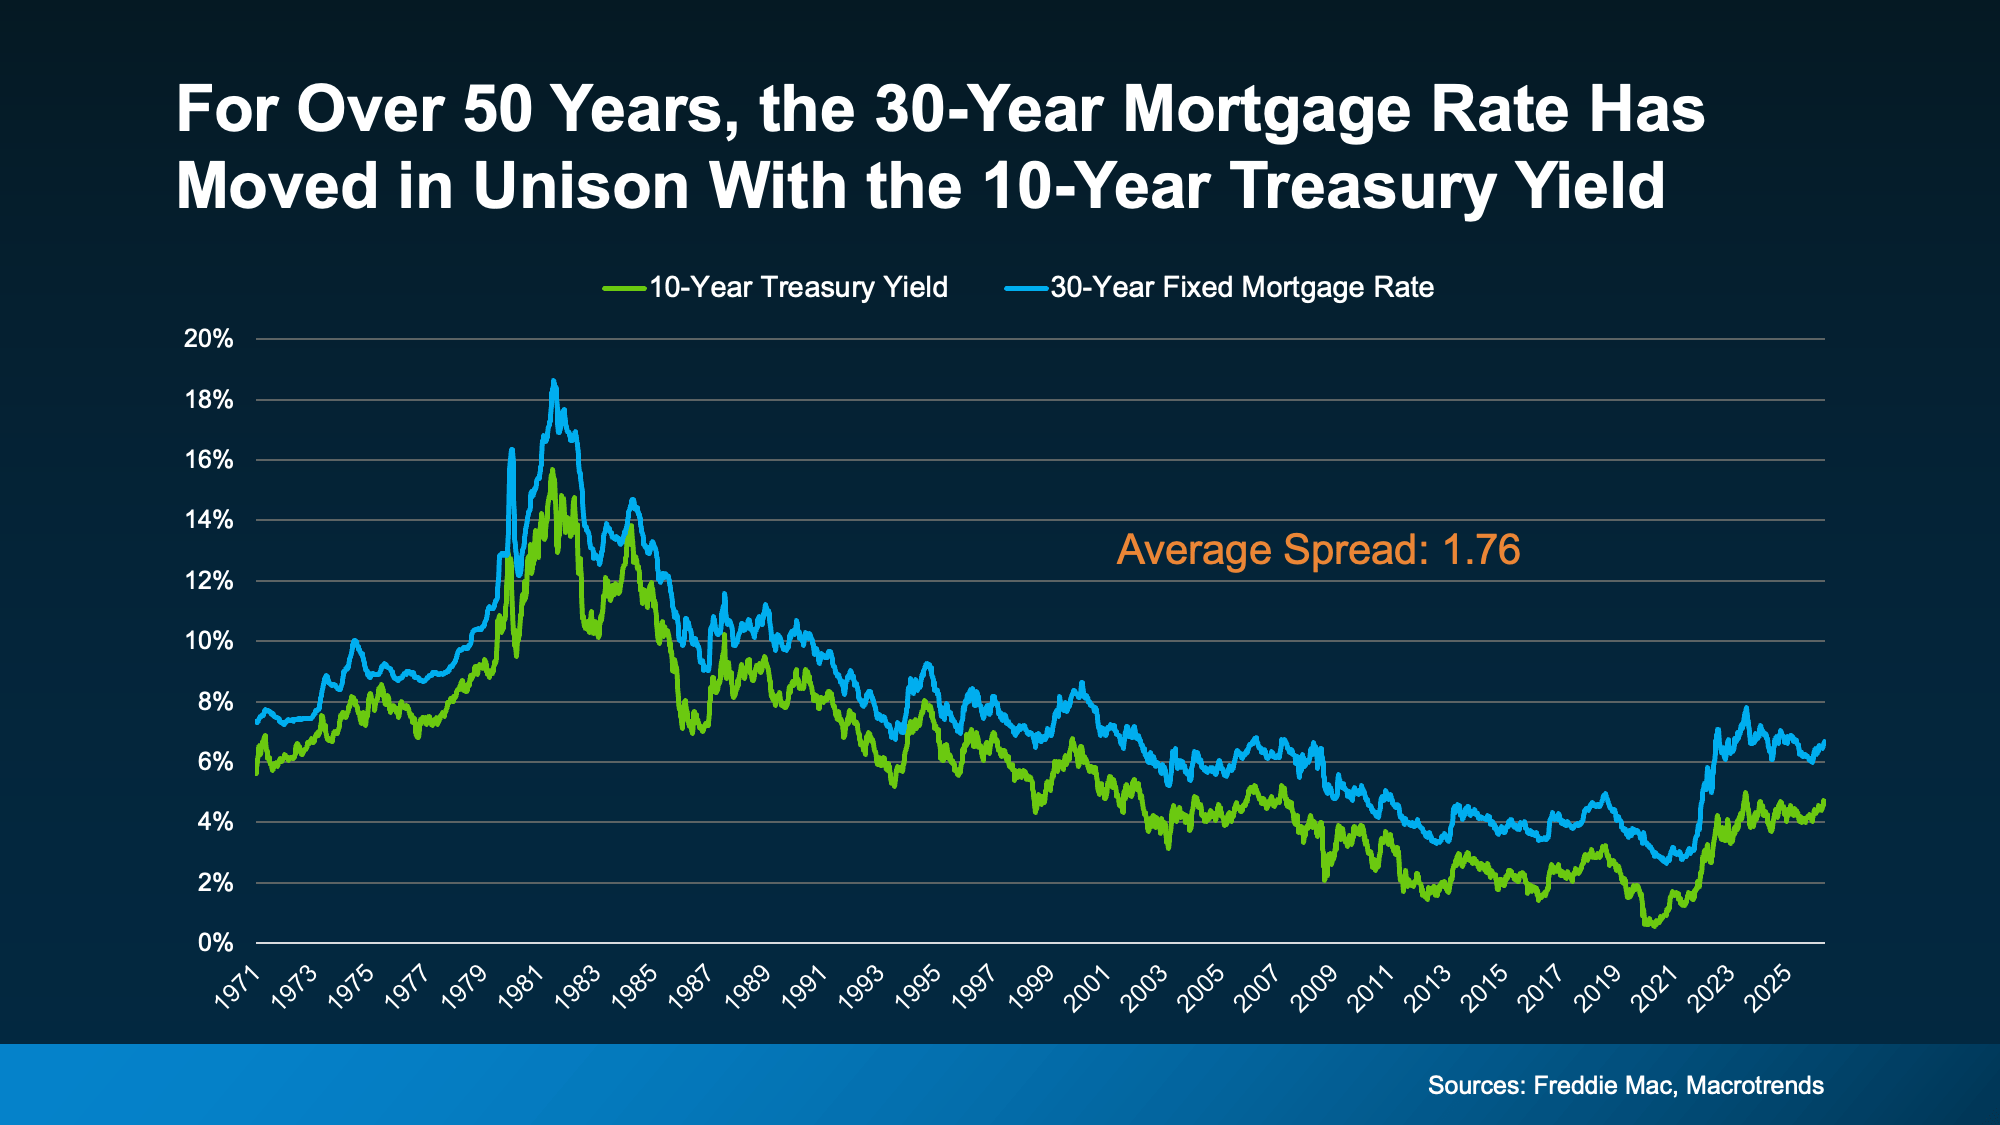
The gap between them is called the “spread.” On average, that gap runs about 1.76 percentage points. And that spread impacts your mortgage rate. A wider spread tends to push mortgage rates higher than the treasury yield alone would suggest, while a narrower spread keeps rates closer to the treasury yield.
If you’re hoping mortgage rates will drop a lot, here’s the reality – they probably won’t, at least not anytime soon. One of the big reasons why comes down to that spread between the 10-year treasury yield and mortgage rates.
A few years ago, that gap got a lot wider as uncertainty in the economy pushed it as high as 3.19 points in 2023.
Now here's the part worth noting – that gap has been narrowing lately. It’s down to about 2.01, just above the long-term average of 1.76 (see graph below):
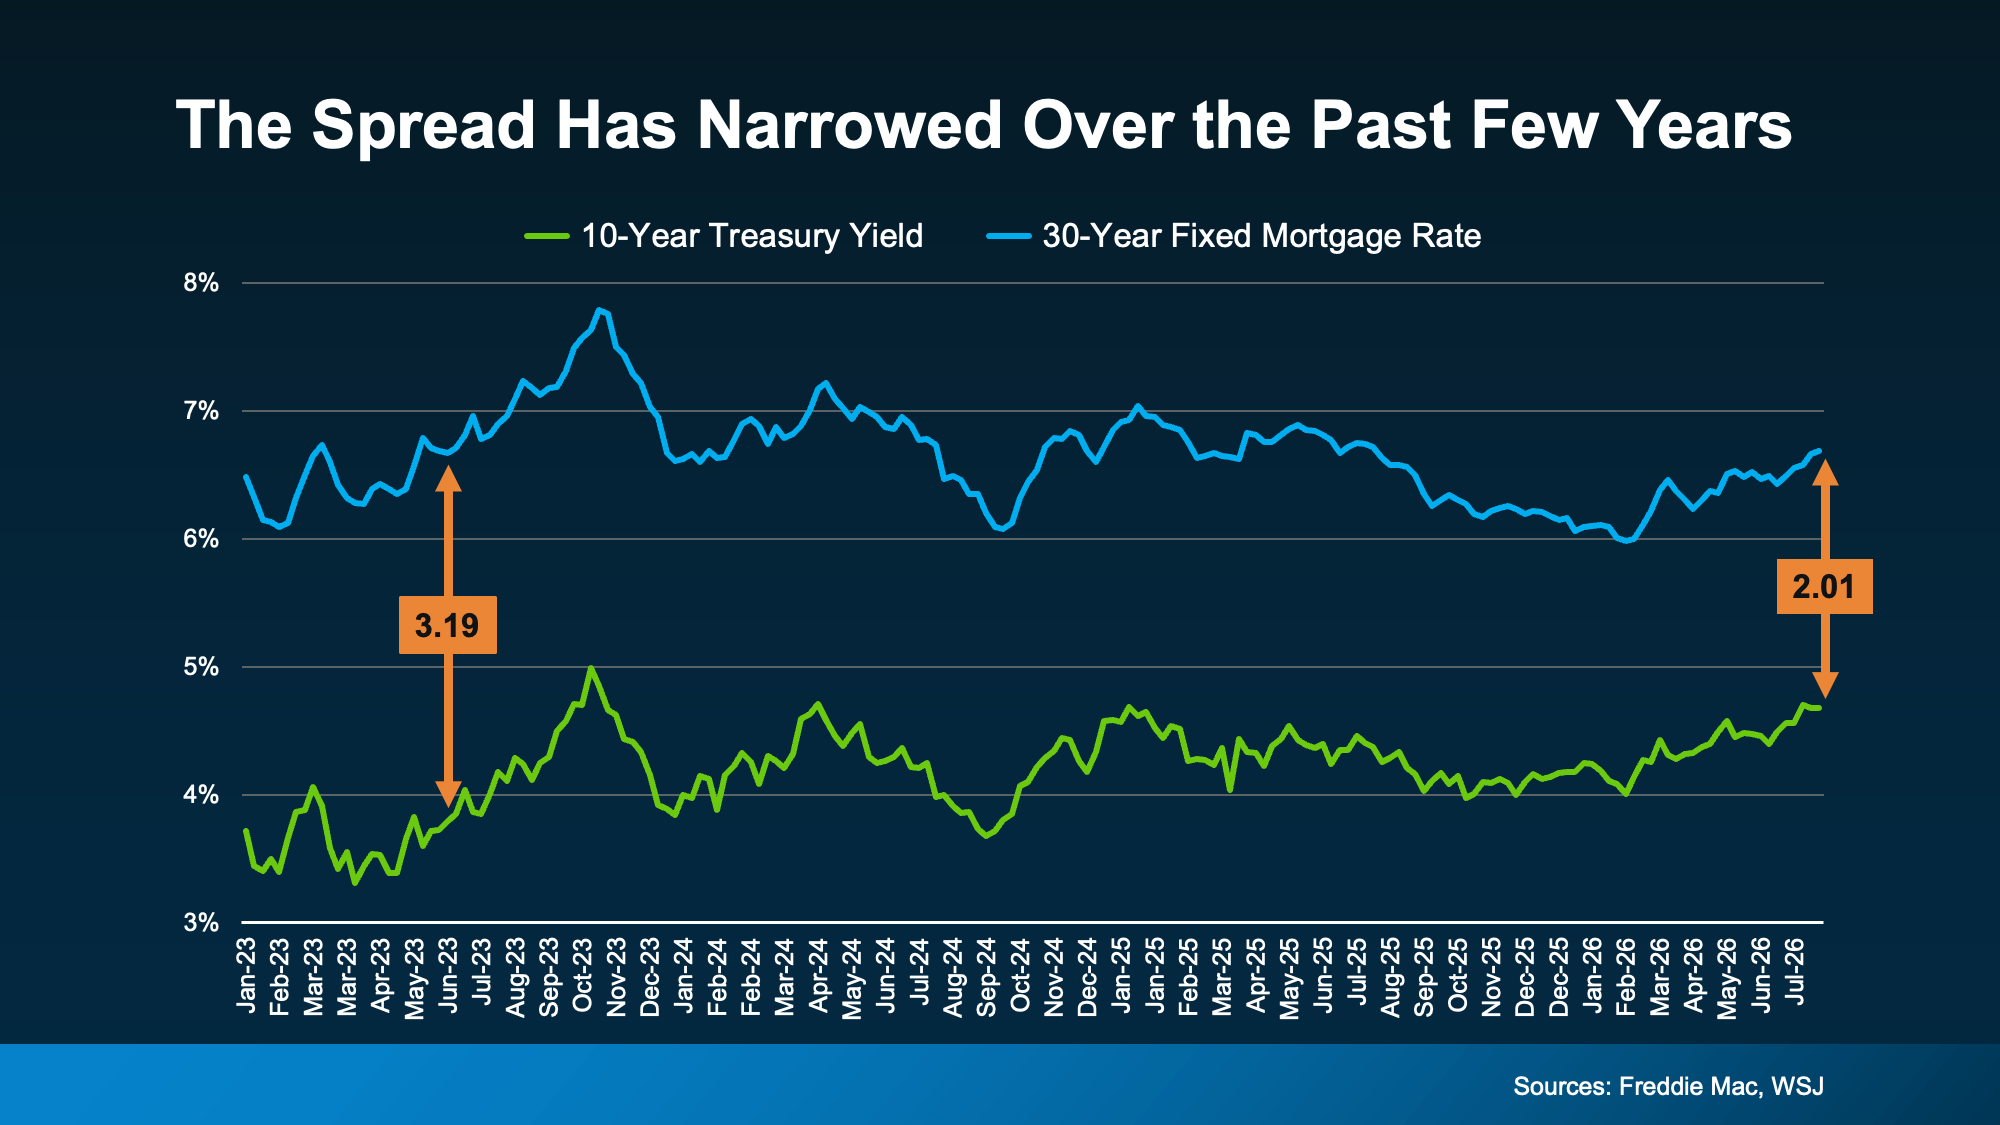
When the gap is wide, there’s more room for rates to fall. But when it’s relatively normal, like it is now, there’s less wiggle room for rates to fall.
Today’s mortgage rate is basically the treasury yield plus the spread. So, when either one moves, your rate moves with it. Here are 3 different rates, all built off today's 10-year treasury yield of 4.68% to show you just how much the spread matters for your bottom line (see graph below):
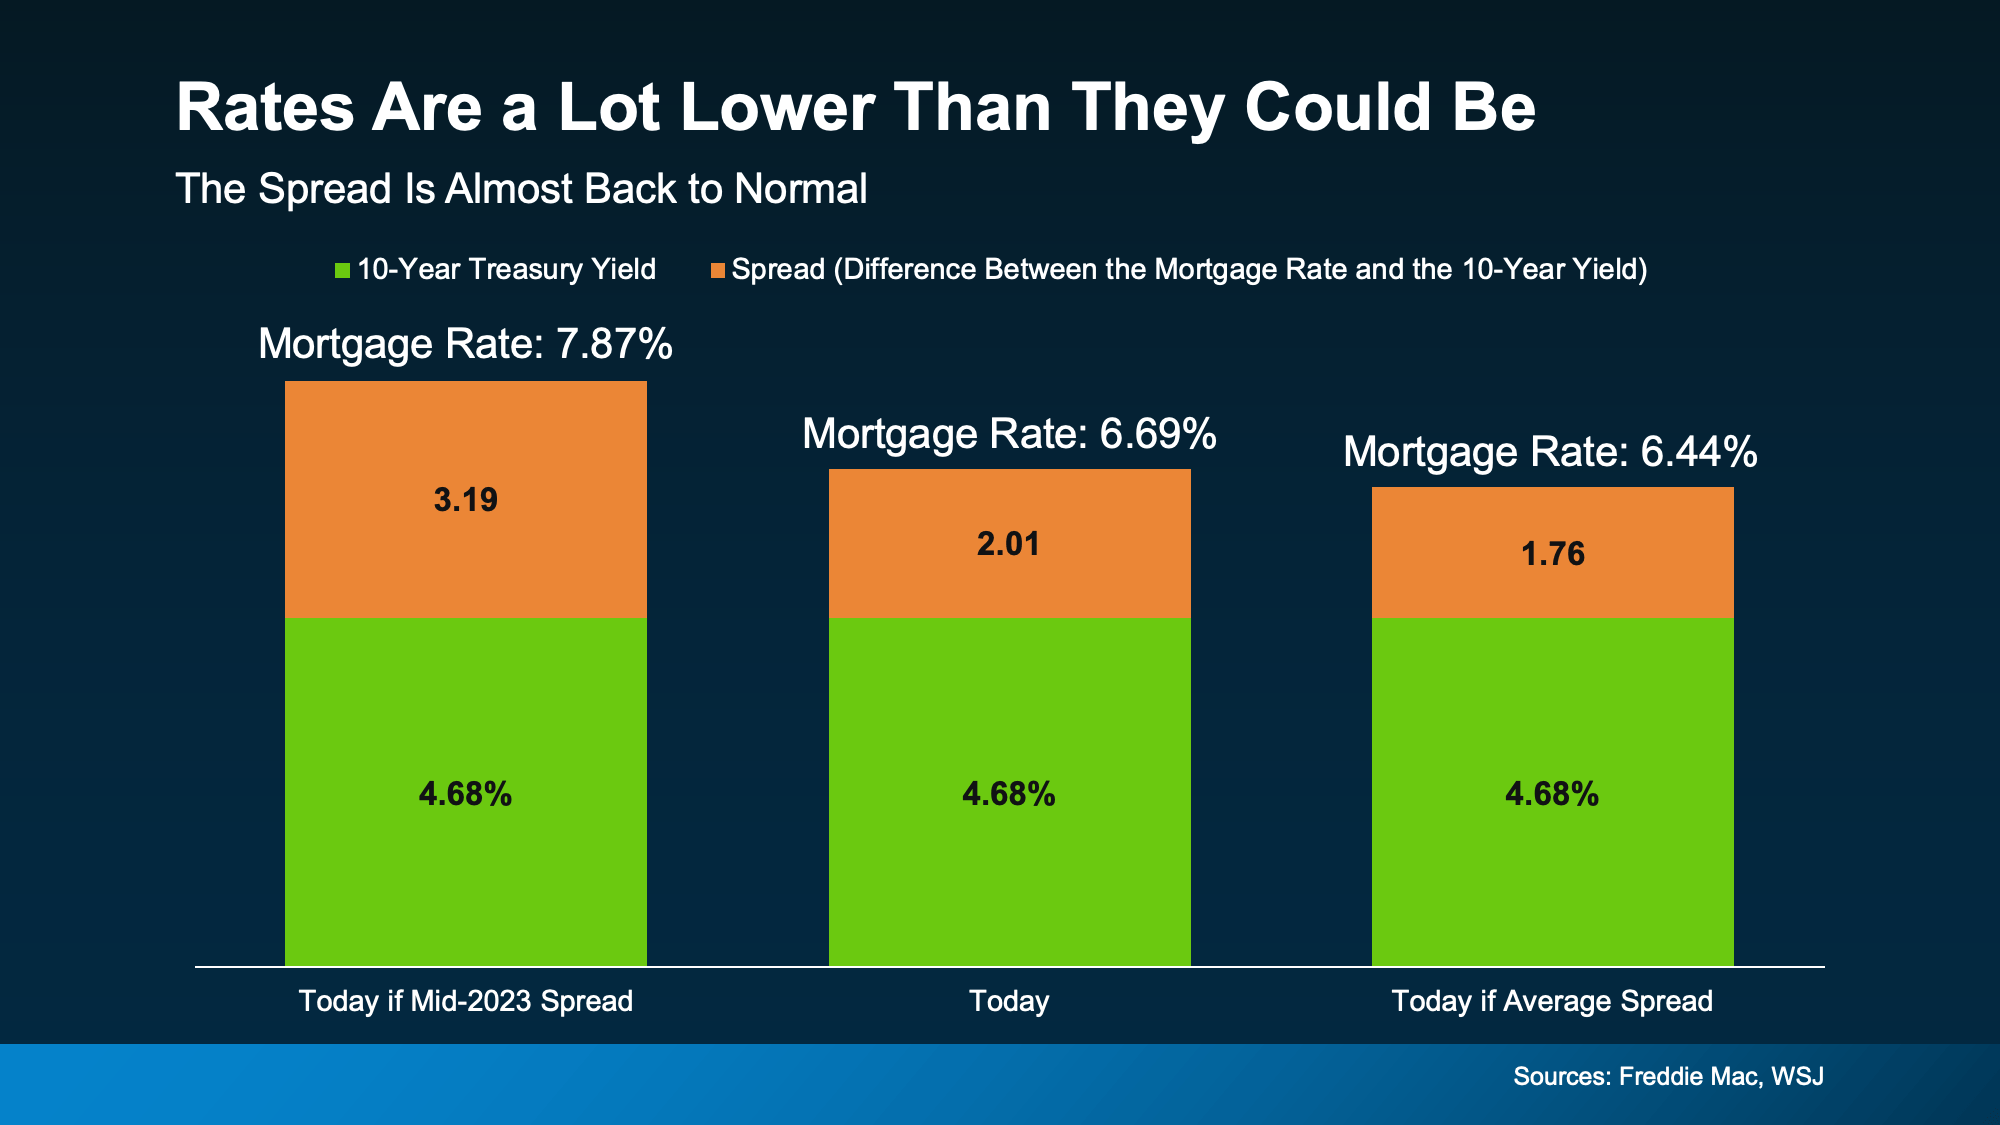
If the spread were still stretched out like it was in 2023, rates would be pushing close to 8% right now. That’s because the spread was over a full point wider than it is today.
But now, thanks to the spread narrowing recently, today's rate sits around 6.69%. That’s the middle scenario in that visual. That's a big difference in your monthly payment compared what we could see if the spread was as big as it was 2023. As Logan Mohtashami, Lead Analyst at HousingWire, put it:
“Of course, mortgage spreads being better in 2026 is the housing hero story of the year . . .”
Now compare that middle bar to the 3rd one. If the spread were sitting at its exact long-term average, rates would be around 6.5%. That's only about a quarter of a point away from where rates actually are today. That means most of the improvement in mortgage rates we should realistically expect from a shrinking spread has already happened.
In other words, the same narrowing spread that’s the reason rates aren’t close to 8% today is also a big reason why they’re not likely to fall a lot further.
That’s the trade-off with a narrowing spread. Rates may not be where you want them, but they're better than they could've been. If you want help figuring out what that means for your monthly payment, reach out to a local lender
#HomeWithRyan #UtahRealtor #UtahRealEstate #EquityRealEstateProsperGroup #LehiUtah #EagleMountainUtah #SaratogaSpringsUtah #UtahCountyHomes #LehiHomesForSale #EagleMountainRealEstate #UtahCountyRealtor #LivingInLehi #MovingToUtahCounty #FirstTimeHomeBuyerUtah #UtahHomeSeller #SellMyHouseUtah #UtahHomeBuying #UtahRelocation #UtahMove #HomeEquityStrategy #MoveUpBuyer #UtahNewConstruction #UtahLife #UtahLiving #FamilyLifeUtah #UtahMountains #SiliconSlopes #UtahInvesting #UtahEntrepreneur #Mortgagerates
My Commitment to YOU!Navigating the world of real estate can feel overwhelming, but you don’t have to face it alone! I’m here to transform the experience of buying or selling your home int....
Today’s housing market splits into four distinct types. You’ve got cash buyers, buyers financing a purchase, owners who feel locked into a low rate, and builders with homes to sell.
If you're trying to buy a home, affordability is probably what keeps you up at night. And as you watch mortgage rates tick up again lately, it’s fair to wonder if you should just hit pause and
Selling your house this fall is absolutely doable. But there’s something you need to know about this time of year. Buyer activity typically starts to slow while the number of homes for
Summer's winding down, and if you've been thinking about selling, you might be wondering if you missed your chance. Better to wait until next year or even next spring, right?Not so fast. About one
 Wasatch Front Regional MLS - Salt Lake Board of REALTORS® All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties
consumers may be interested in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than EQUITY REAL ESTATE® - Prosper Group may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 23, 2026 2:03 PM UTC
Show More...
 Washington County Board of REALTORS® All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be
interested in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than EQUITY REAL ESTATE® - Prosper Group may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 23, 2026 2:17 PM UTC
Show More...
